Search


09/29/2026
Gutting the Community Reinvestment Act would mean fewer financing options for aspiring homeowners, nonprofits and small businesses
Opinion by ULC CEO Aaron Miripol and NDC Executive Director Jonathan Cappelli
In a time where high prices and interest rates make buying a home or growing a business harder than ever, the federal government is gutting yet another resource meant to address these issues: the Community Reinvestment Act (CRA). However, there is still time to write to regulators to protest their plan — if we act by October 13.
The CRA was passed nearly 50 years ago to keep banks from discriminating against people on racial grounds through practices like redlining, when they used race to deny loans to residents of certain neighborhoods. The CRA compels banks to provide mortgages, small business loans, and maintain branches in previously redlined neighborhoods, and support other community services by financing affordable housing development and providing grants to nonprofits.
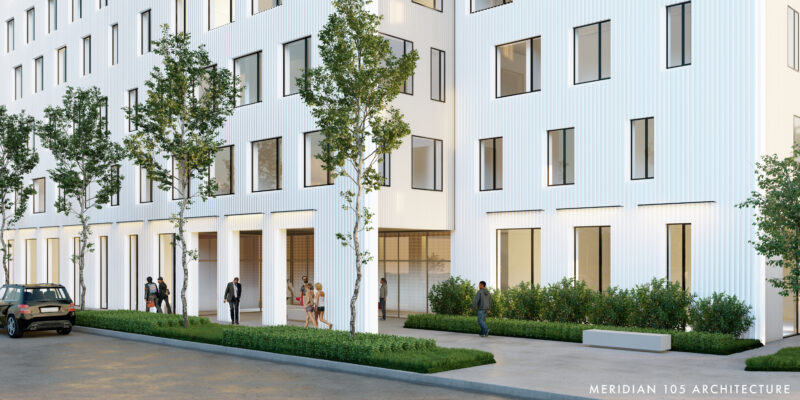
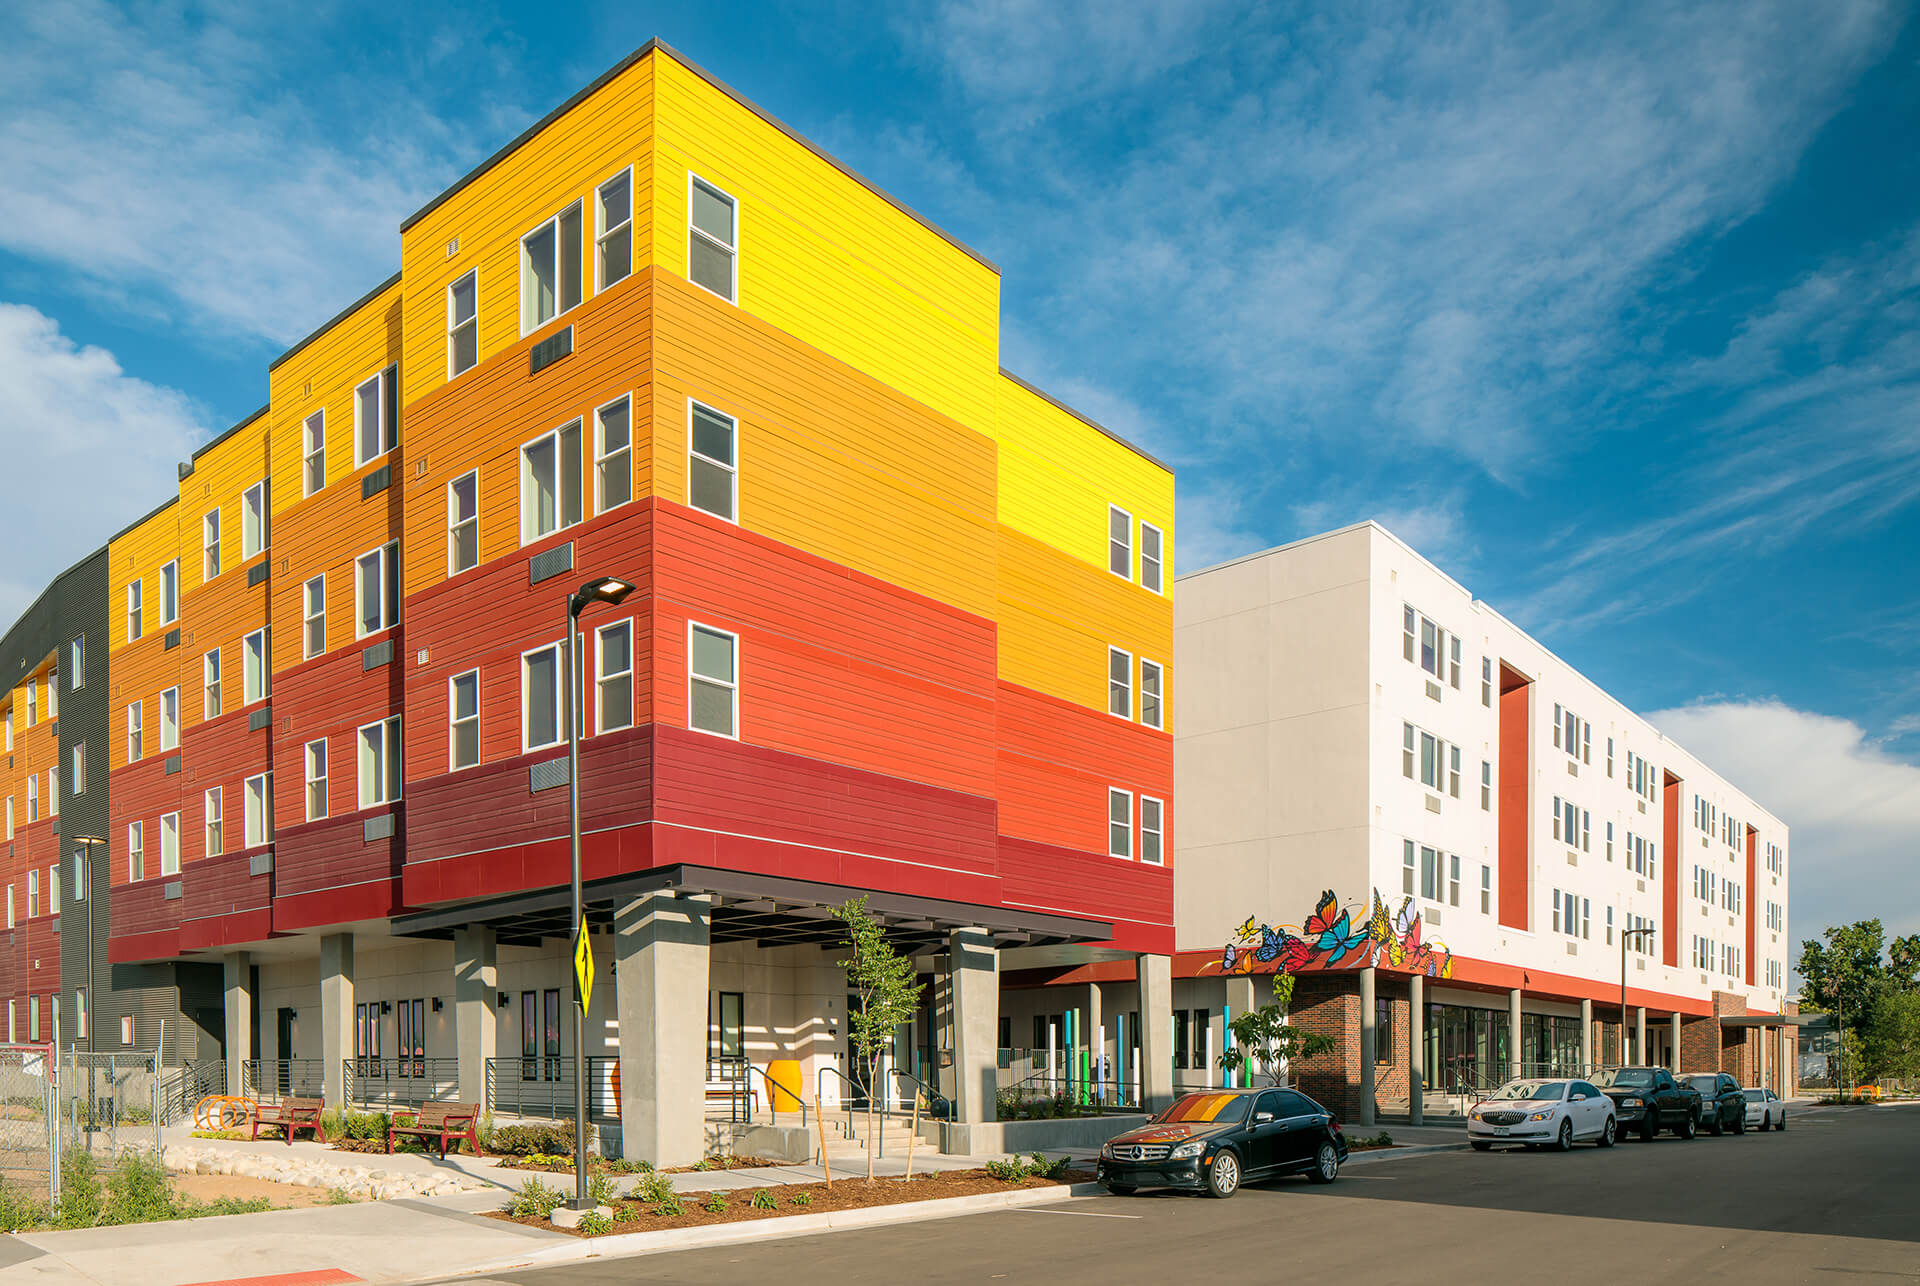
CRA obligations brought $85.5 billion in small business lending and mortgages to the Denver Metro Area in the last 15 years alone. Local nonprofits like Urban Land Conservancy, use these funds to build affordable housing like the all-electric Irving at Mile High Vista, and to acquire and renovate buildings like the Tramway Nonprofit Center which now houses more than a dozen community based organizations in the Cole neighborhood.
The government is now gutting the CRA, proposing new regulations (called “rules”) that would let roughly 97% of banks off the hook for most of their CRA obligations, meaning fewer resources for nonprofits that are keeping people housed and fed, and fewer financing options for small businesses and aspiring homeowners.
It is no surprise that the current federal administration, which already defunded food assistance programs, kicked millions off their health insurance, and cut funding for affordable housing, now has the CRA in its sights. It calls the CRA an “onerous tax on community banks” that funds “activist NGO networks under the guise of community development.” Conveniently, they fail to mention that banks made record profits in 2025 while average Americans had trouble with grocery bills, and homeownership is increasingly out of reach for young people as they struggle to pay rent. While banks may consider needing to provide equitable business and housing opportunities “a tax”, it’s one they can certainly afford to pay.
As a coalition of nonprofit affordable housing developers who use CRA funds to provide homes for those who can’t afford them otherwise, we see the benefits the CRA brings to our community. While the regulators claim that these changes bring “clarity and ensure that community development resources reach intended communities”, we believe they are an attempt to defund programs that serve the working class and keep people from accessing financial services. These changes to the CRA do nothing for our neighbors who want to become homeowners or open a small business, but will instead help the largest banks widen the profit margins even further.
We have one recourse: submit your thoughts here by October 13, 2026 to let the federal regulators know that we don’t need to be helping the banks, but instead need to keep our neighbors fed and housed.
###